

Giving credit where credit is due
Nonprofit provider Ogen brings a new dimension to Israeli banking
The cost of living in Israel is higher than in almost any other country, Sagi Balasha said. “Many people cannot afford daily life. They cannot save; they cannot buy apartments.”
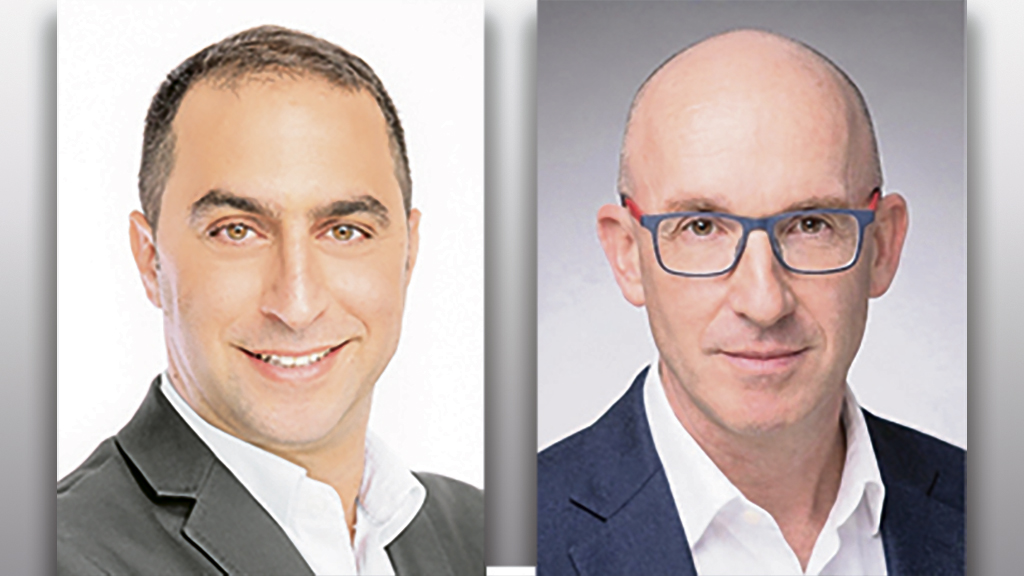
Mr. Balasha is the CEO of Ogen, a nonprofit credit provider in Israel. He and Eldan Kaye, Ogen’s vice president of development and partnerships, talked about it with groups in Hoboken, Englewood, and Teaneck last week.
“In the last two decades, Israel really grew financially from being a developing country to being a developed country,” Mr. Balasha said. “But the wealth is not distributed in a way that most Israelis can enjoy it.” He sees the banking system in Israel as a major factor. And he sees Ogen — that’s Hebrew for “anchor” — as positioned to help significantly.
Ogen makes loans to low-income individuals, small businesses, and nonprofits, Mr. Balasha said. It is the largest nonprofit lender in Israel, and “the need for its services is immense. “In the United States, you have 4,500 banks, meaning you have a bank for every 77,000 people. In Israel, you only have seven banks. That means one bank for every 1.4 million people.”
There is also no real competition between the banks, he continued. “Those seven banks are quite similar to each other. They’re all targeting high- income people and big businesses, and they’re marginalizing, or not giving enough attention to, low-income people and small businesses. And therefore, you have many people in Israel who are unbanked or underbanked and people that have no access to credit.”
The United States has “community banks, credit unions, and community development financial institutions supporting financial inclusion. All that doesn’t exist in Israel.”
“The market failure is vast,” Mr. Kaye said. “There are about 600,000 small businesses in Israel. They employ 45 percent of the population and they contribute 54 percent of Israel’s GDP. This is a critical component of Israel’s economy, yet the risk policies and the risk appetite of the banks result in a starvation of capital of these small businesses.
“When you look at families, individuals, we’re talking about 1.5 million people who are either unbanked — in other words, have no bank accounts whatsoever — or underbanked — they have a bank account, but they will receive poor service, high fees, and unviable products.”
Israel has about 16,000 active nonprofits, Mr. Kaye continued. “Fourteen billion shekels of government funds are allocated to these nonprofits to carry out work that the government is stepping away from. Yet when these nonprofits go to the banks, unless they have a building or an asset, the banks will never lend to them.”
So Ogen’s vision is to “be a part of really building the economy from the ground up.”
Ogen’s goal is to provide both access to credit and affordable credit, Mr. Balasha said. The organization provides interest-free loans to individuals and families and low-interest loans to small businesses and nonprofits.
The organization is apolitical and areligious, Mr. Kaye said. “Anyone who holds an Israeli ID card is eligible.” And the loans it provides are relatively short term. Some of the products it offers are up to eight or 10 years, “but as a whole, 80 to 90 percent of our portfolio is five-year loans.”
The loans are also relatively small, he continued, generally up to about $12,000 or $13,000 to individuals. “They’re not mortgages at this stage,” but some are used to help with down payments. “For small businesses, the average loan is around $120,000.” These types of loans might be used for a variety of purposes, including to start a new business, finance a business expansion, or meet cash-flow needs. Loans to nonprofits “will range anywhere between about $100,000 to about a $1 million, but the $1 million loans are really for building projects, for capital projects.”
Ogen offers “a wide variety of tools,” Mr. Kaye continued. “We have loans for farmers, we have loans for reservists, we have loans that are based around debt consolidation that come with financial coaching and help negotiating down debt, and loans for credit-score building. There’s a variety of different products that we provide, all with the aim of really supporting these populations that are not being sort of given a leg up by the banking system.”
But Ogen does not see its products as appropriate for everyone in these populations. “We probably reject around 60 to 70 percent of loan applications,” Mr. Kaye said. “The majority of these cases are on the basis of repayment capability. Because we’re not being judged on profits, this is about helping people; if there’s a slight chance that someone won’t be able to repay it, then a loan is not the right tool for them.”
Often applicants who are not approved initially can work with financial coaches to “build up their repayment capabilities, then come back for a loan,” Mr. Kaye continued. “For example, we have this incredible program with a couple of foundations for women leaving violent relationships. Often the violence is not only physical, it’s also financial. Around 45 percent of the women who joined the program were rejected for an Ogen loan initially, but after working with these financial coaches, they came back and were approved, and they’re all paying on time.
“So it’s about the responsible nature of the lending.”
That responsibility extends both to the organization itself, to ensure that proceeds are likely to be repaid so they can be loaned again in the future, and to applicants, Mr. Kaye said. “Someone who stops paying is harmed. Their credit scores go down.”
Ogen’s focus on loans, rather than handouts, is “a matter of sustainability,” Mr. Balasha said. “Giving a loan, you get most of your money back, and then you can recycle it. You can give the same money again and again.
“A handout is very important to people who cannot receive loans,” he added. But if Ogen gave handouts, “we could maybe give 10 percent of what we can give in the current model.”
Ogen’s decision to charge some interest was also made in an effort to expand its reach. It was founded in 1990 as a free loan organization; the decision to charge interest was made 10 years ago, after Mr. Balasha joined. Doing so enabled the organization to fund its operations with impact investing in addition to philanthropy, he said. “We understood that raising only philanthropy would keep us too small to meet the huge demand in Israel.”
Since then, the organization has grown significantly. “The reason we are growing is that we are blending sources of finance,” Mr. Balasha said. “Meaning we are not just raising philanthropy, we are also raising other sources of capital — we are issuing bonds, we are getting credit lines from commercial banks, we have deposits.”
The bonds are issued to large institutional investors, including pension funds and insurance companies, Mr. Balasha continued. Investors “get a market rate return, and parallel to that, they get a bonus because they help to do some social good.” That is also the case for the credit lines. “We pay market rate interest to the banks — it’s not charity whatsoever. The only element that is kind of combined is deposits. We call them impact loans — depositors get a moderate return.
“We are blending all these types of finance, which is very pioneering for Israel. And therefore, we were able to really expand and help more Israelis. Today Ogen lends about 10 times more than we lent 10 years ago in terms of amounts and in terms of borrowers. The size of our fund is 10 times larger.”
Ogen also expanded its services during that time and now offers financial coaching, guidance, and mentoring. “This year, we are mentoring 4,500 people, small businesses and nonprofits,” Mr. Balasha said.
“Around 50 percent of what we lend comes from philanthropy and 50 percent comes from other resources,” Mr. Kaye said. “But the aim is to change that.
Ogen has applied to the Bank of Israel to become the country’s first nonprofit bank,” he added.
Now only large investors and foundations can legally make deposits, or in Ogen terminology, impact loans, Mr. Balasha said. Once the organization qualifies as a bank, “anyone can open an account and deposit whatever amount you want to deposit. We can then raise more funds for more lending.”
Mr. Kaye joined Ogen four years ago. One of the things that really drew him to the organization was “the understanding that philanthropy is finite, and its resources and its ability to meet market failures and hopefully solve them,” are also finite, he said. “Ogen’s ability to really leverage philanthropy in a very significant way is, to my mind, the sort of solution and the future of philanthropy.
“I think that as Israelis, as a people, we have to look at innovative models of philanthropy, because the needs are endless. So the scaling here, I think, is what matters, because otherwise there are so many people who are left unserved.”
Mr. Kaye also sees another benefit to Ogen’s model of lending rather than giving. “There’s something about the dignity that comes with a loan,” he said. “We see this with our reservists, for example. We’re about to cross the 100-million-shekel mark in terms of loans to reservists. This is a community of families that have served hundreds of days since October 7. They’re not here for handouts. They got caught up in this economic crisis due to the fact that they want to safeguard the country. And for them, the repayment is the dignity; it’s ‘I don’t need a handout. I can build myself back up, but I need someone to trust me and to give me the opportunity.’”
Mr. Balasha sees Ogen’s model as “a macroeconomic solution for Israel.
“It’s not a niche,” he concluded. “It’s something big that if we succeed can really move the needle for millions of Israelis. It can be a banking solution. We can be the eighth bank, but a very different type of bank. And it can be a game changer for Israel.”